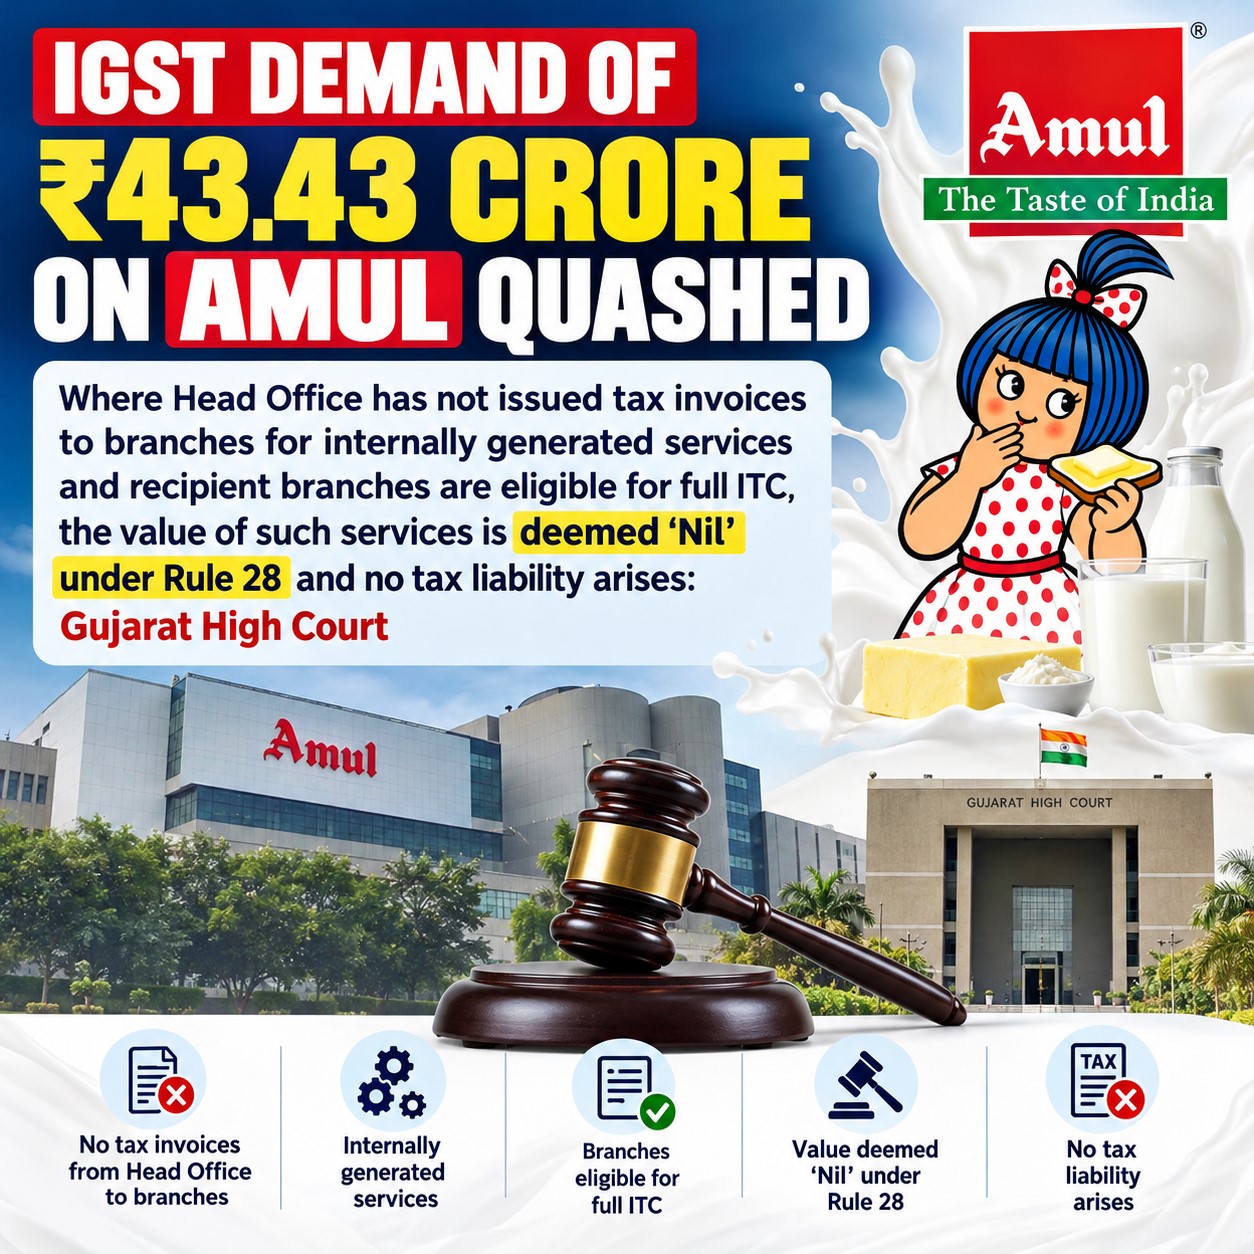
The Court held that following the omission of Rule 96(10) without any saving clause, pending proceedings cannot survive and the taxpayer is entitled to refund.
The Gujarat High Court has directed the revenue to process a refund claim within twelve weeks, following the settled legal position on the omission of Rule 96(10) of the CGST Rules, 2017, as affirmed by the Supreme Court in Goodluck India Ltd. v. Union of India [M/s. Sudeep Industries v. Union of India & Ors.].
The bench of Justices A.S. Supehia and Vaibhavi D. Nanavati noted that the petitioner held various Advance Authorizations for procurement of raw materials exempt from IGST under Notification No. 79/2017-Customs. The petitioner had claimed refund of amounts comprising IGST, interest, and penalty that had not been re-credited to its Electronic Credit Ledger for the financial years 2019-20 to 2021-22.
The respondent had summarily rejected the refund claim on the very date the petitioner filed its detailed reply to the show-cause notice, without affording an opportunity of hearing. The Court noted that the refund claim was filed in light of the omission of Rule 96(10) vide Notification No. 20/2024-Central Tax dated 08.10.2024.
The Supreme Court in Goodluck India Ltd. had held that the omission of Rule 96(10) is prospective and that no saving clause was incorporated — thereby bringing to an end all pending proceedings. The Gujarat High Court had previously followed this position in MAC Industry v. Union of India and Maldeep Catalysta Pvt. Ltd. v. Union of India. Following these precedents, the Court quashed the rejection order and directed the respondents to process the refund within twelve weeks.
2026-juristway.com-3067-HC(Gujarat)-GST