
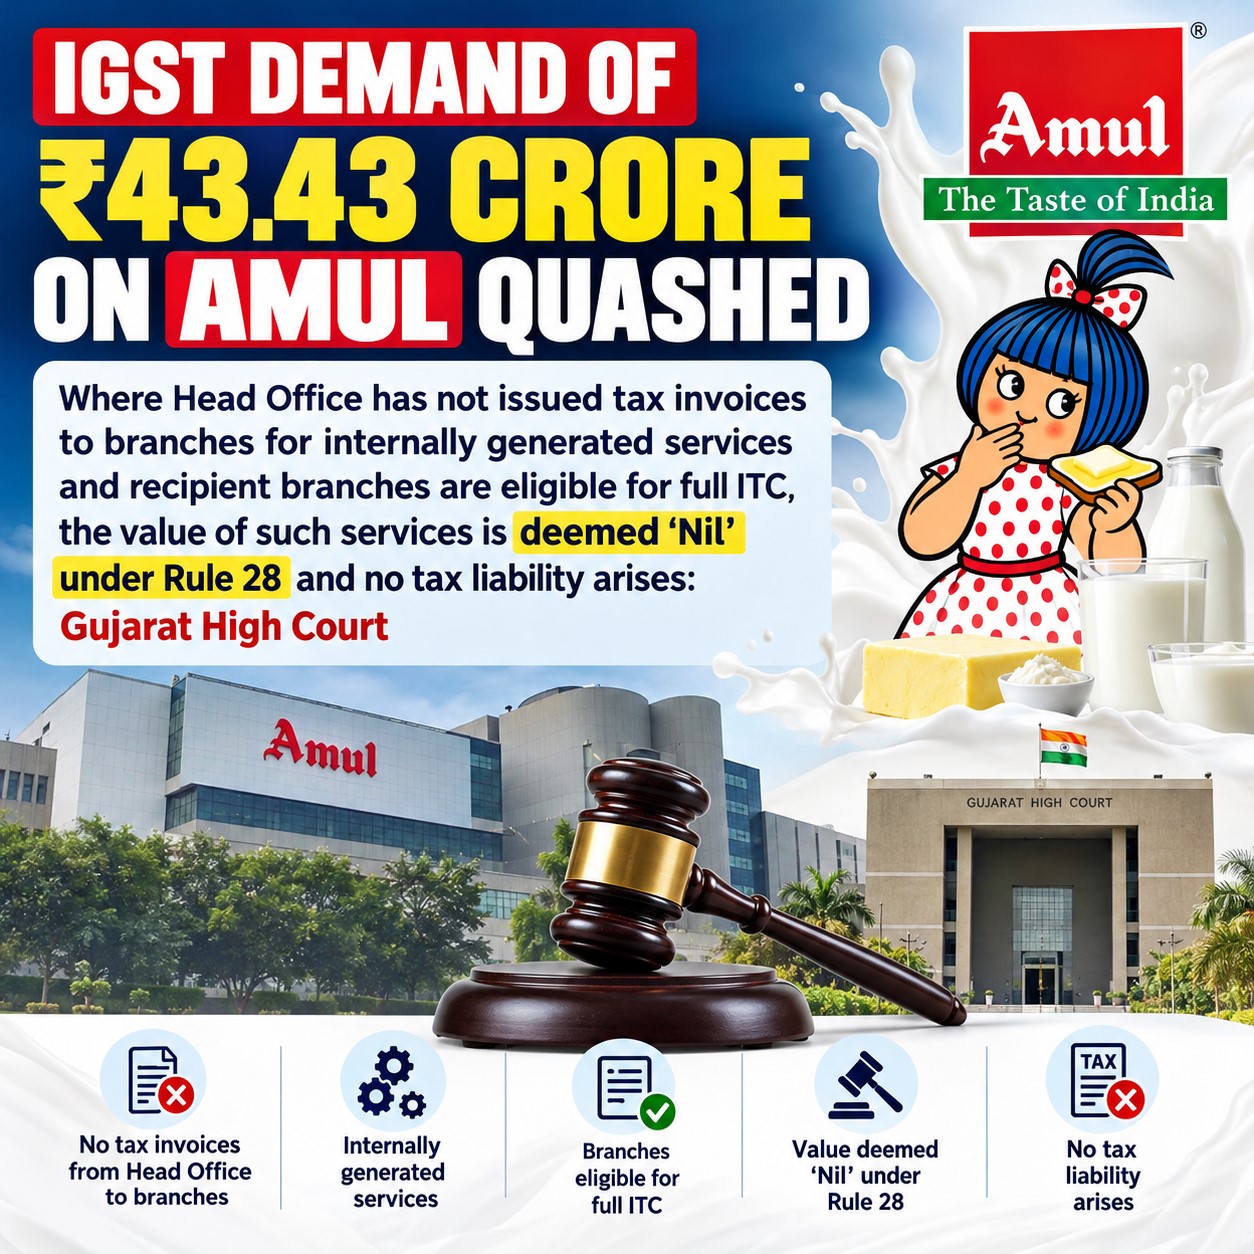
IGST demand of ₹43.43 crore on Amul quashed • Eight appeals filed by MRF Limited before different State Benches of GSTAT transferred to the Principal Bench… • Confiscation order passed on the same day as the show cause notice • "Communication" under Section 107(1) means actual communication to the person aggrieved • Retrospective cancellation of a supplier's registration does not by itself render inadmissible the input tax… • Cash cannot be seized under Section 67(2) of the CGST Act • Section 147A of the Income Tax Act declared unconstitutional • Penalty confirmed in the adjudication order cannot exceed penalty proposed in the show cause notice
#GST
272 articles
Eight appeals filed by MRF Limited before different State Benches of GSTAT transferred to the Principal Bench…
The President of the GSTAT, exercising powers under Section 109(5) of the CGST Act for the first time, held that where multiple appeals pending before different…

Retrospective cancellation of a supplier's registration does not by itself render inadmissible the input tax…
The Principal Bench held that a buyer who has done everything the law requires on the date of purchase holds his credit regardless of what the Department may la…
Penalty confirmed in the adjudication order cannot exceed penalty proposed in the show cause notice
The Court held that Section 75(7) of the CGST Act is mandatory and once the legislature has forbidden the adjudicating authority from confirming any demand in e…
Refund cannot be appropriated against a demand for which statutory pre-deposit has been made and appeal is pending
The Court held that once the prescribed pre-deposit of 20% of the disputed demand has been made and an appeal has been filed, recovery of the balance demand sta…
Circular restricting inverted duty refund where input and output are the same is inapplicable where ITC…
The Division Bench, led by the Chief Justice, held that CBIC Circular No. 135/5/2020-GST addresses only the narrow situation where ITC accumulates on account of…
Showing 1–10 of 272 articles